
Buying your first home in Burnaby is exciting — and, if we’re being honest, a little overwhelming. Between pre-approvals, offers, strata documents, and neighbourhoods you’ve only ever driven through, it’s easy to feel like everyone speaks a language you never learned. The good news: it’s far more manageable than it looks once you understand the path. Here’s the same walkthrough I give every first-time buyer, so you know what’s coming before it arrives.
1. Get your financing sorted before you fall in love
The single most important first step has nothing to do with looking at homes. Before we tour a single listing, talk to a mortgage broker or your bank and get pre-approved. A pre-approval does three things: it tells you your real budget, it often locks in an interest rate for a set window, and it makes your offer dramatically stronger when the right place appears. In a competitive market like Greater Vancouver, a pre-approval isn’t optional — it’s your starting line. Shopping without one is like walking into a negotiation with no idea what you can actually spend.
2. Budget for the full cost, not just the price
The number on the listing is only part of the story. First-time buyers are often caught off guard by the closing costs that stack up on top of the purchase price. Plan for:
- Property Transfer Tax — though first-time buyers may qualify for a full or partial exemption, which is absolutely worth checking.
- Legal or notary fees to handle the conveyancing.
- A home inspection — never skip this to win a bid; it can save you tens of thousands.
- Moving costs, and a small cushion for the surprises that always come with a new place.
If you’re buying a condo or townhome, you’ll also have ongoing monthly strata fees. I’ll always help you read the strata documents, meeting minutes, and depreciation report carefully — that’s where the real story of a building hides.
3. Use the programs built for people like you
First-time buyers in British Columbia have access to incentives that experienced buyers don’t — exemptions, registered savings plans designed for a down payment, and more. These programs change over time, so we’ll look at what’s current and what you actually qualify for. A little homework here can put real money back in your pocket.
4. Match the neighbourhood to your life, not just your budget
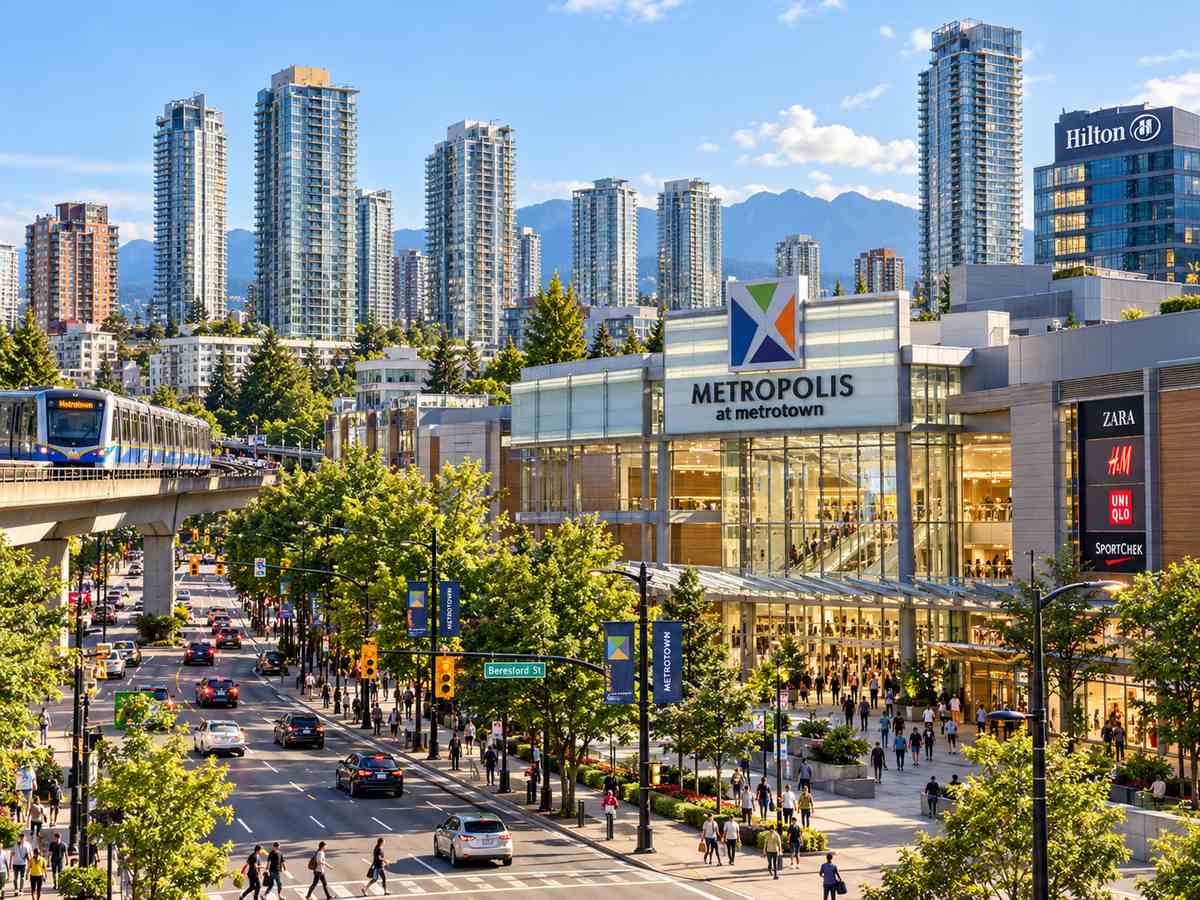
Burnaby isn’t one market — it’s many. Metrotown offers walkable, transit-connected condo living. Brentwood is modern and fast-growing. Capitol Hill and Burnaby Lake lean quieter and more residential. The “right” neighbourhood is the one that fits how you actually live: your commute, the SkyTrain, where you’ll grab groceries, and where you can see yourself in five years. We’ll spend real time on this, because changing neighbourhoods later is expensive.
5. Understand what you’re really buying
Condo, townhome, or detached house — each comes with trade-offs. Condos are the most affordable entry point and the lowest-maintenance, but you’ll live with strata rules and shared decisions. Townhomes offer more space and often a bit of outdoor area. Detached homes give you the most freedom and land, at the highest price. There’s no universally “best” choice — only the one that fits your budget, lifestyle, and plans.
6. Make a smart, well-supported offer
When we find it, we won’t guess. We’ll look at recent comparable sales, the property’s condition, and current demand to build an offer that’s competitive but not reckless. Subjects — conditions like financing and inspection — protect you, and we’ll use them wisely. The goal is never just to win; it’s to win at the right price, on terms that keep you safe.
7. The closing stretch
Once your offer is accepted, there’s a short, busy period: finalizing financing, completing the inspection, removing subjects, and handling the legal work. It can feel intense, but this is exactly where having someone in your corner pays off. I’ll keep every moving part on track so the only thing you have to think about is where the couch goes.
Keep your financing steady while you search
A pre-approval tells you the most a lender is willing to offer, but your comfortable budget usually sits a little below that ceiling. Build a simple monthly picture that adds up the mortgage payment, strata fees, property tax, insurance, utilities, and a small maintenance cushion, then ask yourself whether that number still leaves room for the rest of your life.
Just as important, protect your file between pre-approval and completion. Lenders look for stability, so try to avoid the moves that can unsettle an approval at the last minute:
- Changing jobs or switching from salaried to self-employed income without talking to your lender first.
- Opening new credit, such as a car loan, a new credit card, or financing for furniture.
- Moving large sums of money around without a clear paper trail for your down payment.
If something does change, tell your mortgage professional early. Surprises are far easier to solve before subjects are removed than after.
Tour like a buyer, not a browser
Showings are designed to impress, so it helps to focus on the things you cannot easily change. Notice natural light and which way the windows face. Stand quietly in the bedrooms and listen for traffic, neighbours, or mechanical noise. If you work from home, check your cell signal. In condos and townhomes, ask about recent and upcoming maintenance, and look for signs of how the building is cared for in the hallways, parkade, and common areas.
Do not dismiss older buildings too quickly. A well-maintained older strata can offer larger rooms, more storage, and a friendlier price than the newest tower down the street. If you are weighing a pre-sale, balance the appeal of a brand-new home against construction timelines and finishes you have only seen in renderings, whereas a resale home lets you see exactly what you are getting. Take notes and photos after each visit; by the fourth showing, the details start to blur.
Think about your next move, too
Your first home does not have to be your forever home. For many buyers, it is the step that builds equity, teaches you what you actually want in a place, and sets up the next purchase. That makes resale potential worth considering from day one.
A few questions help: Would this layout appeal to a wide range of future buyers? Is it close to transit, schools, and everyday amenities? Does the building or complex have a good maintenance record? Is parking or storage included? Homes that check these boxes tend to be easier to sell or rent out later, which gives you more flexibility if your job, family, or priorities change. Choosing well now keeps your options open when it is time to upsize, invest, or move on.
Ready when you are
There’s no rush and no pressure. If you’re even thinking about buying in the next year, a single conversation now will save you stress later — and cost you nothing. Reach out anytime and we’ll talk it through at your pace.